
Shopping for Personal Insurance?
Is Personal/Home Insurance Liabilities and Coverage Something That Is Included in your Insurance Policy?
Liability Insurance Explained
Homeowners or renters insurance – available to cover liability if you injure someone on your
property, as well as cover items and assets within your home, among other coverages.
Umbrella insurance – Extra liability protection that works with other policies, typically the higher levels of coverage are not included as a standard handset.
Learn More About our Insurance Offerings!
Get in contact with our qualified agents right away!
Liability Coverage from Personal Insurance Policies
Medical Payments to Others: This is a homeowners insurance coverage that will likely pay on small personal injury claims that happen in your home regardless if you are at fault or not. Let’s try to picture an example scenario: It’s the 4th of July and your buddy went across the border to Wisconsin to grab some POWERFUL fireworks. He gets them back and asks if you want to light some off. Little does he know, he got a dud firework and you are about to regret his invitation. He loads up a spinning mortar round into some PVC, instead of it shooting off into the sky it explodes right there at his feet. He is somehow fine, but you get hit by some of the PVC and you need medical attention. Who pays here? The supplier? Your friend’s insurance policy? Ask our agent to review your policy and see if you need better coverage for those “Hold my Beer” moments. Because we enjoy fun as much as the next person, but you could be slammed by large bills if you aren’t covered enough. Just because nothing has happened yet, doesn’t mean nothing will.
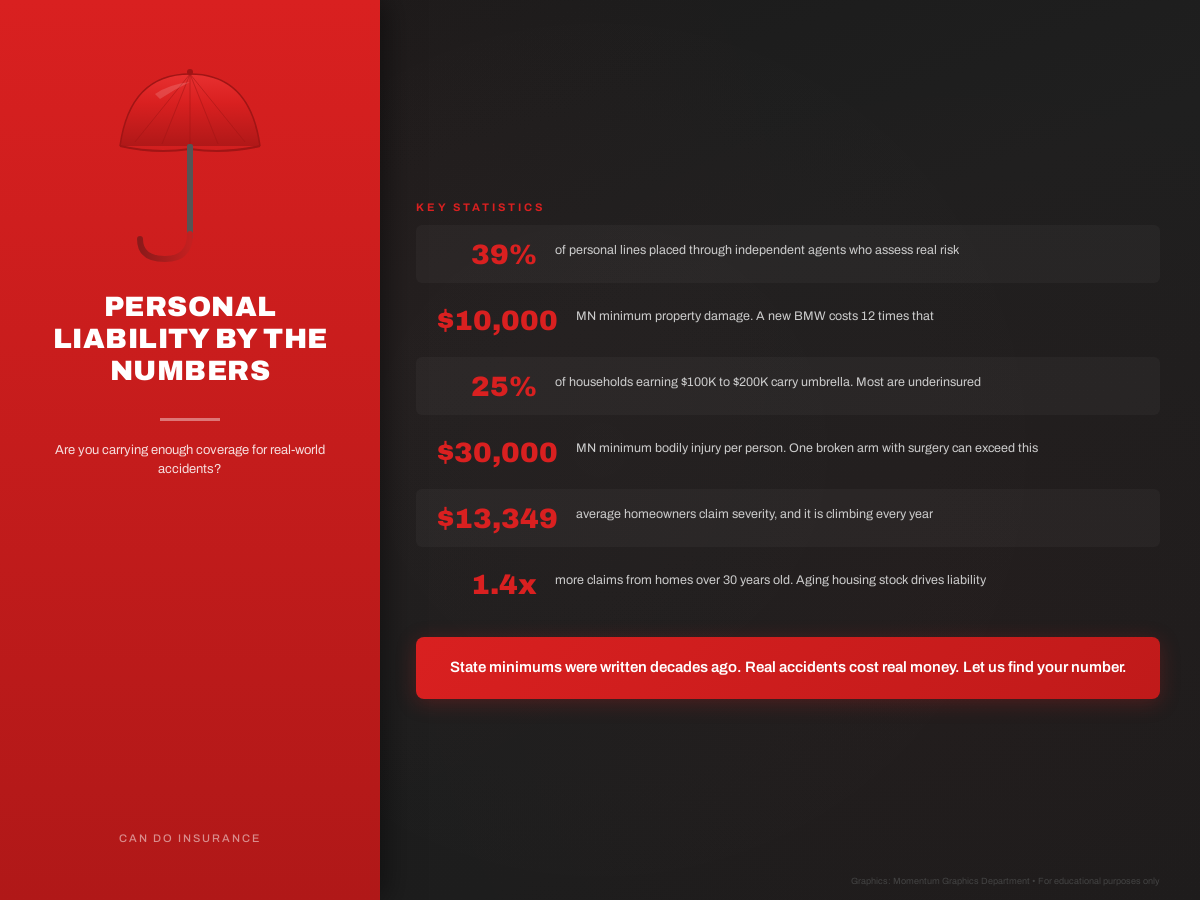
A Personal Umbrella Policy (PUP) is a type of umbrella policy that adds a layer of coverage over and above your liability policies offering higher limits for when these other coverages have been exhausted, usually on the underlying auto insurance and home/renters. If you’re in a car wreck that results in major medical bills that your auto policy liability limit is unable to cover, an umbrella extends those limits and picks up the extra costs. Let’s imagine a worst-case scenario here: You are driving your “daily driver” car, a reliable Honda Fit in wintertime and you DON’T have insurance. Nice little go-getter, but isn’t the best in winter. You suddenly start to spin out on the freeway and unfortunately slam into that expensive-looking BMW that was driving next to you. After all is said and done, they want you to cover the cost of replacing it out of pocket would run you over $120,000 to replace their shiny new car. Without proper coverage, you could have to cover the difference. The following statement is the most common basic insurance coverage in Minnesota as an example “$30,000 bodily injury liability per person. $60,000 bodily injury liability per accident. $10,000 property damage liability per accident. $25,000 uninsured motorist bodily injury per person.” This coverage would be woefully unable to cover that $120,000 bill from that BMW. This is where an umbrella coverage would step in and help cover additional costs or fully pay the bill. Crashes happen every day, don’t be caught without enough coverage!
Personal Liability Insurance Explained
Property Damages You Cause: Most policies will cover any damage you do to someone else’s property, whether it be through a vehicle accident or destruction of another person’s assets, property, ETC.
Other People’s Medical Expenses, Lost Wages, Pain & Suffering: In case an accident is your fault. This coverage can also cover settlements if you are sued.
While affordable insurance policies depend on the insurer and location, these basic coverages are often included in personal liability insurance. Please remember that these policies do not include intentional acts. For instance, if you intentionally vandalize someone else’s property under no circumstance would this account for liability coverage.
Person Liability Coverage: Common Exclusions
Protecting Against Injury or Damage to Your Property: Liability coverage is designed only for a third party, not against damage to your property. Liability coverage is not related to you damaging your car or home , that would be a collision/comp (for auto policies) or a homeowners insurance event.
Incidents Related To Business: Personal liability insurance generally excludes incidents such as business activities. If you have a home-based business, you might also require different liability insurance coverage for incidents involving clients or employees.
Family Members: Homeowners insurance will not provide coverage for injuries that happen to the residents of the insured property (i.e. members of your family). Health insurance covers medical expenses for injuries to members of the household, not personal liability.
Finding the Correct Amount of Liability Coverage
Review Your Lifestyle: If you entertain others often or have a pool, for example, your risk profile can increase, so it might be worth springing from higher liability cover.
Buy an Umbrella Insurance policy: An umbrella policy is inexpensive and offers extra protection if you have a big claim. They also cover liabilities not included in your current policies, like charges of slander or libel.
Is Liability/Personal and umbrella coverage for me?
With liability insurance, you should always take into consideration your assets and lifestyle as well as the situations that might result in a lawsuit to decide an appropriate coverage limit. There are several points to consider below:
Does umbrella insurance provide overseas protection?
Is Libel and Slander Covered by Umbrella Insurance?
Even if I don’t have other policies, can I still get umbrella insurance?
The short answer is yes, because life is unpredictable and not having coverage for that ONE time you need it, will forever haunt your memories and wallet. The long answer is Absolutely because of the above-mentioned reasons. Not having coverage for one incident could financially ruin you and leave you reeling for years to come. If you’ve got an accident-prone friend, if you drive in a state with bad winters (Case in point Minnesota), for all those variables that you can’t ever predict, like other people. What happens when there is an especially bad storm that rips a tree out and drops it onto your roof or through your car? Or a massive hailstorm that ruins your siding? Having these protections can save you thousands when the bill comes due.
Insure yourself against the future with Can Do Insurance
Insurance is not just another policy, but a financial backstop that provides additional protection, potential for future savings, and unmatched peace of mind. No matter where you’re navigating life’s risks – throughout the Midwest – a Can Do Insurance policy makes sure that life doesn’t have unexpected twists and turns for which you weren’t prepared. Reach out to Can Do Insurance today and learn how a tailored insurance policy can help protect you, your family, and your financial assets for countless years in the future.